News analysis ·
Visa, Mastercard swipe fee deal: who pays the card fee
Visa and Mastercard ask a judge to finalize their swipe fee settlement. We trace how interchange flows and who would carry the cost under the new terms.
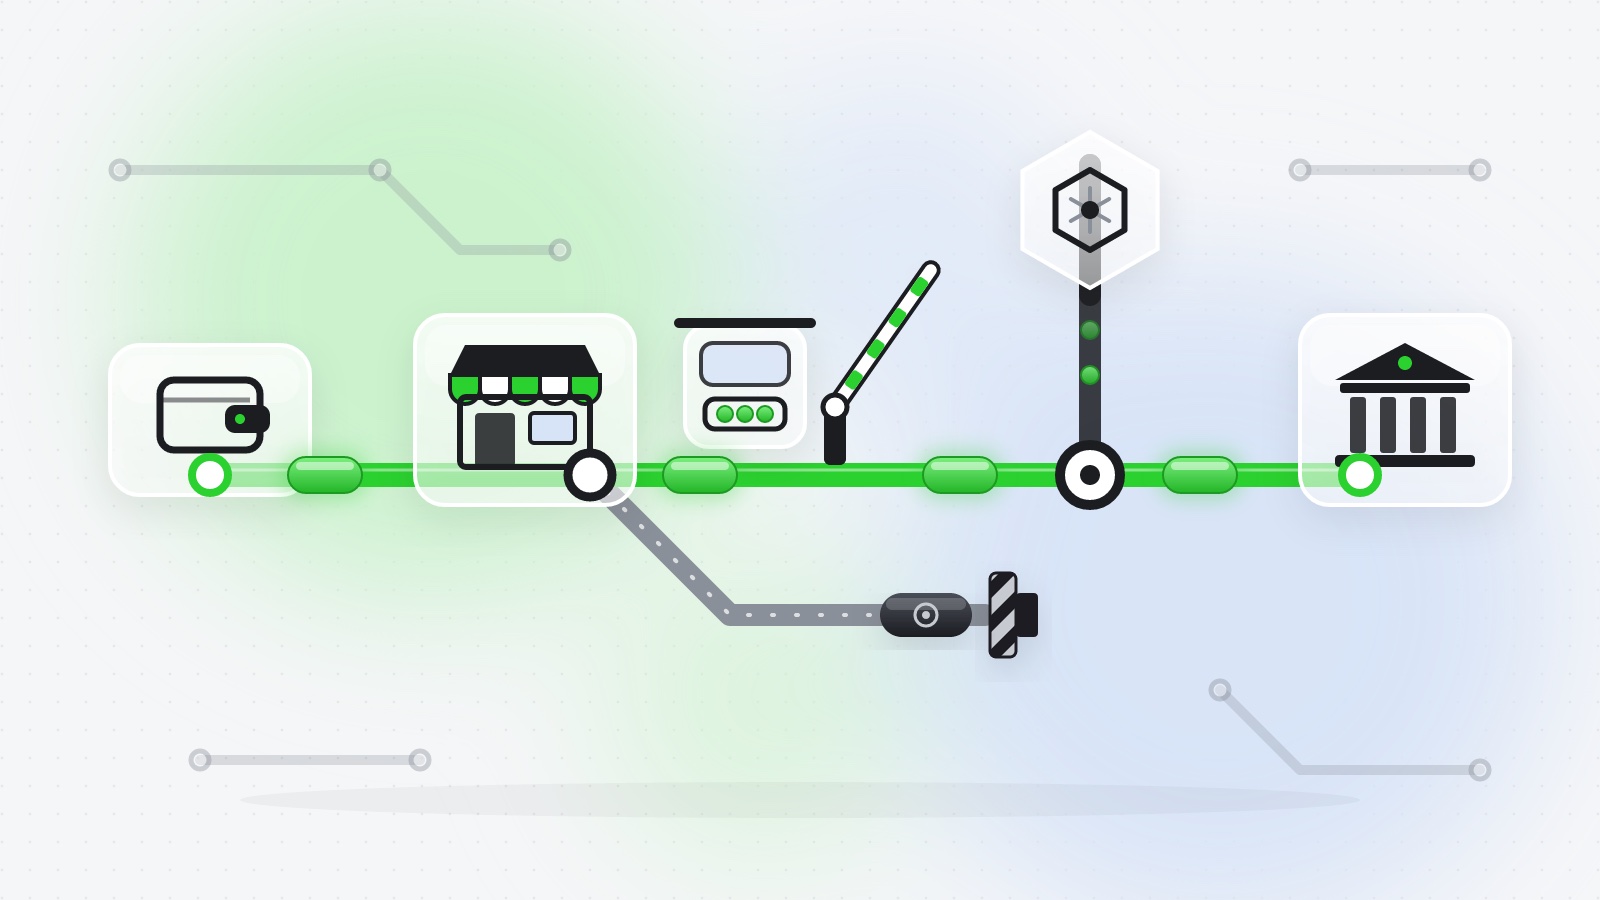
Visa and Mastercard have asked a federal court to give final approval to their settlement with merchants over card swipe fees, Payments Dive reported. Walmart and large retail trade groups want the deal blocked. This article looks at what the terms would change in the flow of a card payment, and who would end up paying for it.
What happened in court
The case is old. Merchants first sued over swipe fees in 2005. Class lawyers for merchants and the card networks agreed the current settlement a year ago. U.S. District Judge Brian Cogan gave it preliminary approval in June, finding it better than a 2024 settlement the court had turned down.
In their latest filing, the networks argued that the objectors bring nothing new. According to Payments Dive, Visa and Mastercard wrote that "the objections merely reprise the same arguments this Court already considered and rejected". They also said objections from the National Retail Federation and the Retail Industry Leaders Association should count for little, because several member companies support the deal. And they asked the court to reject Walmart's claim that keeping it inside the class is an unjust taking of its legal claim.
The networks added a warning: merchants would probably lose at trial, and any class win would be appealed. That is their argument, not a finding by the court.
How the money moves on a card swipe
When a shopper pays by credit card, the merchant does not receive the full price. The merchant's bank, called the acquirer, pays out the sale minus a fee. The largest slice of that fee is interchange: a charge that flows from the acquirer to the bank that issued the card. Visa and Mastercard set the interchange schedules and take their own network fees on top, but most of the interchange money goes to issuing banks.
Issuers use that income to fund card rewards. That is why premium cards with travel points and cashback usually carry higher interchange. The merchant pays more to accept them, and the shopper sees the rewards, not the cost.
Per the Nilson Report, cited by Payments Dive, merchants paid an average fee of 2.35% on Visa and Mastercard transactions in 2024. Under the settlement, credit interchange rates would fall by 10 basis points for five years. A basis point is a hundredth of a percentage point. Standard consumer credit cards would carry a 1.25% rate for eight years.
The rule change that matters most
The rate trims are modest. The bigger shift is in who decides which cards a store takes. Today the honor all cards rule says that a merchant who accepts any card from a network must accept all of them. The deal would let merchants refuse some pricier premium and commercial credit cards branded Visa or Mastercard.
Stores could also charge extra on card payments or give price cuts for other methods, as ways to steer shoppers toward cheaper cards. In plain terms, the settlement hands merchants tools to push part of the cost of expensive cards back toward the people who choose them.
- Refuse: decline certain premium or commercial cards at the till.
- Surcharge: add a fee to card payments that cost more to accept.
- Discount: reward shoppers who pay with a cheaper method.
Large merchants say these tools are weaker than they look. Turning away a popular rewards card risks losing the sale, so many stores may keep accepting them and keep paying.
Who carries the cost and the risk
If merchants use the new tools, the burden moves. Shoppers holding premium cards could face surcharges or refusals. Issuing banks could see less interchange on cards that merchants decline, which puts pressure on how they fund rewards. If merchants do not use the tools, the cost stays where it is today: built into the merchant's fee and, often, into the prices every shopper pays, whatever method they use.
There is also a legal risk for the parties themselves. A settlement only binds once a judge approves it. If the court rejects it, the case goes back toward trial and appeals, and none of the fee changes take effect.
Lawyers' fees are part of the fight. Plaintiffs' counsel objected on Thursday to a $36 million fee request from 18 merchant-plaintiffs that had settled damages claims in a related case. That group, which includes The Gap, Yum! Brands, Dick's Sporting Goods and Crate & Barrel Holdings, says it helped improve the terms compared with the deal from two years ago. If that award is granted, proposed fees for class counsel would drop to $170 million.
What to watch
Class counsel filed their reply to the objections under seal on Wednesday. Judge Cogan told the lawyers to propose redactions by Monday, so he can balance confidentiality against the public's right to see the filing. The next markers are that redaction decision, the ruling on the objector fee request, and above all whether final approval is granted.
For people in payments, the practical question is behavioural. Watch whether acquirers and checkout providers build easy ways for merchants to decline or surcharge specific card types, and whether large retailers actually use them.
Sources
- Payments Dive, 16 Oct 2026
Written by AI from the sources above and published automatically: before release, a script confirms every figure against the sources and checks for copied text. No editor reviews it. Treat it as background reading, not financial advice.